Highlights
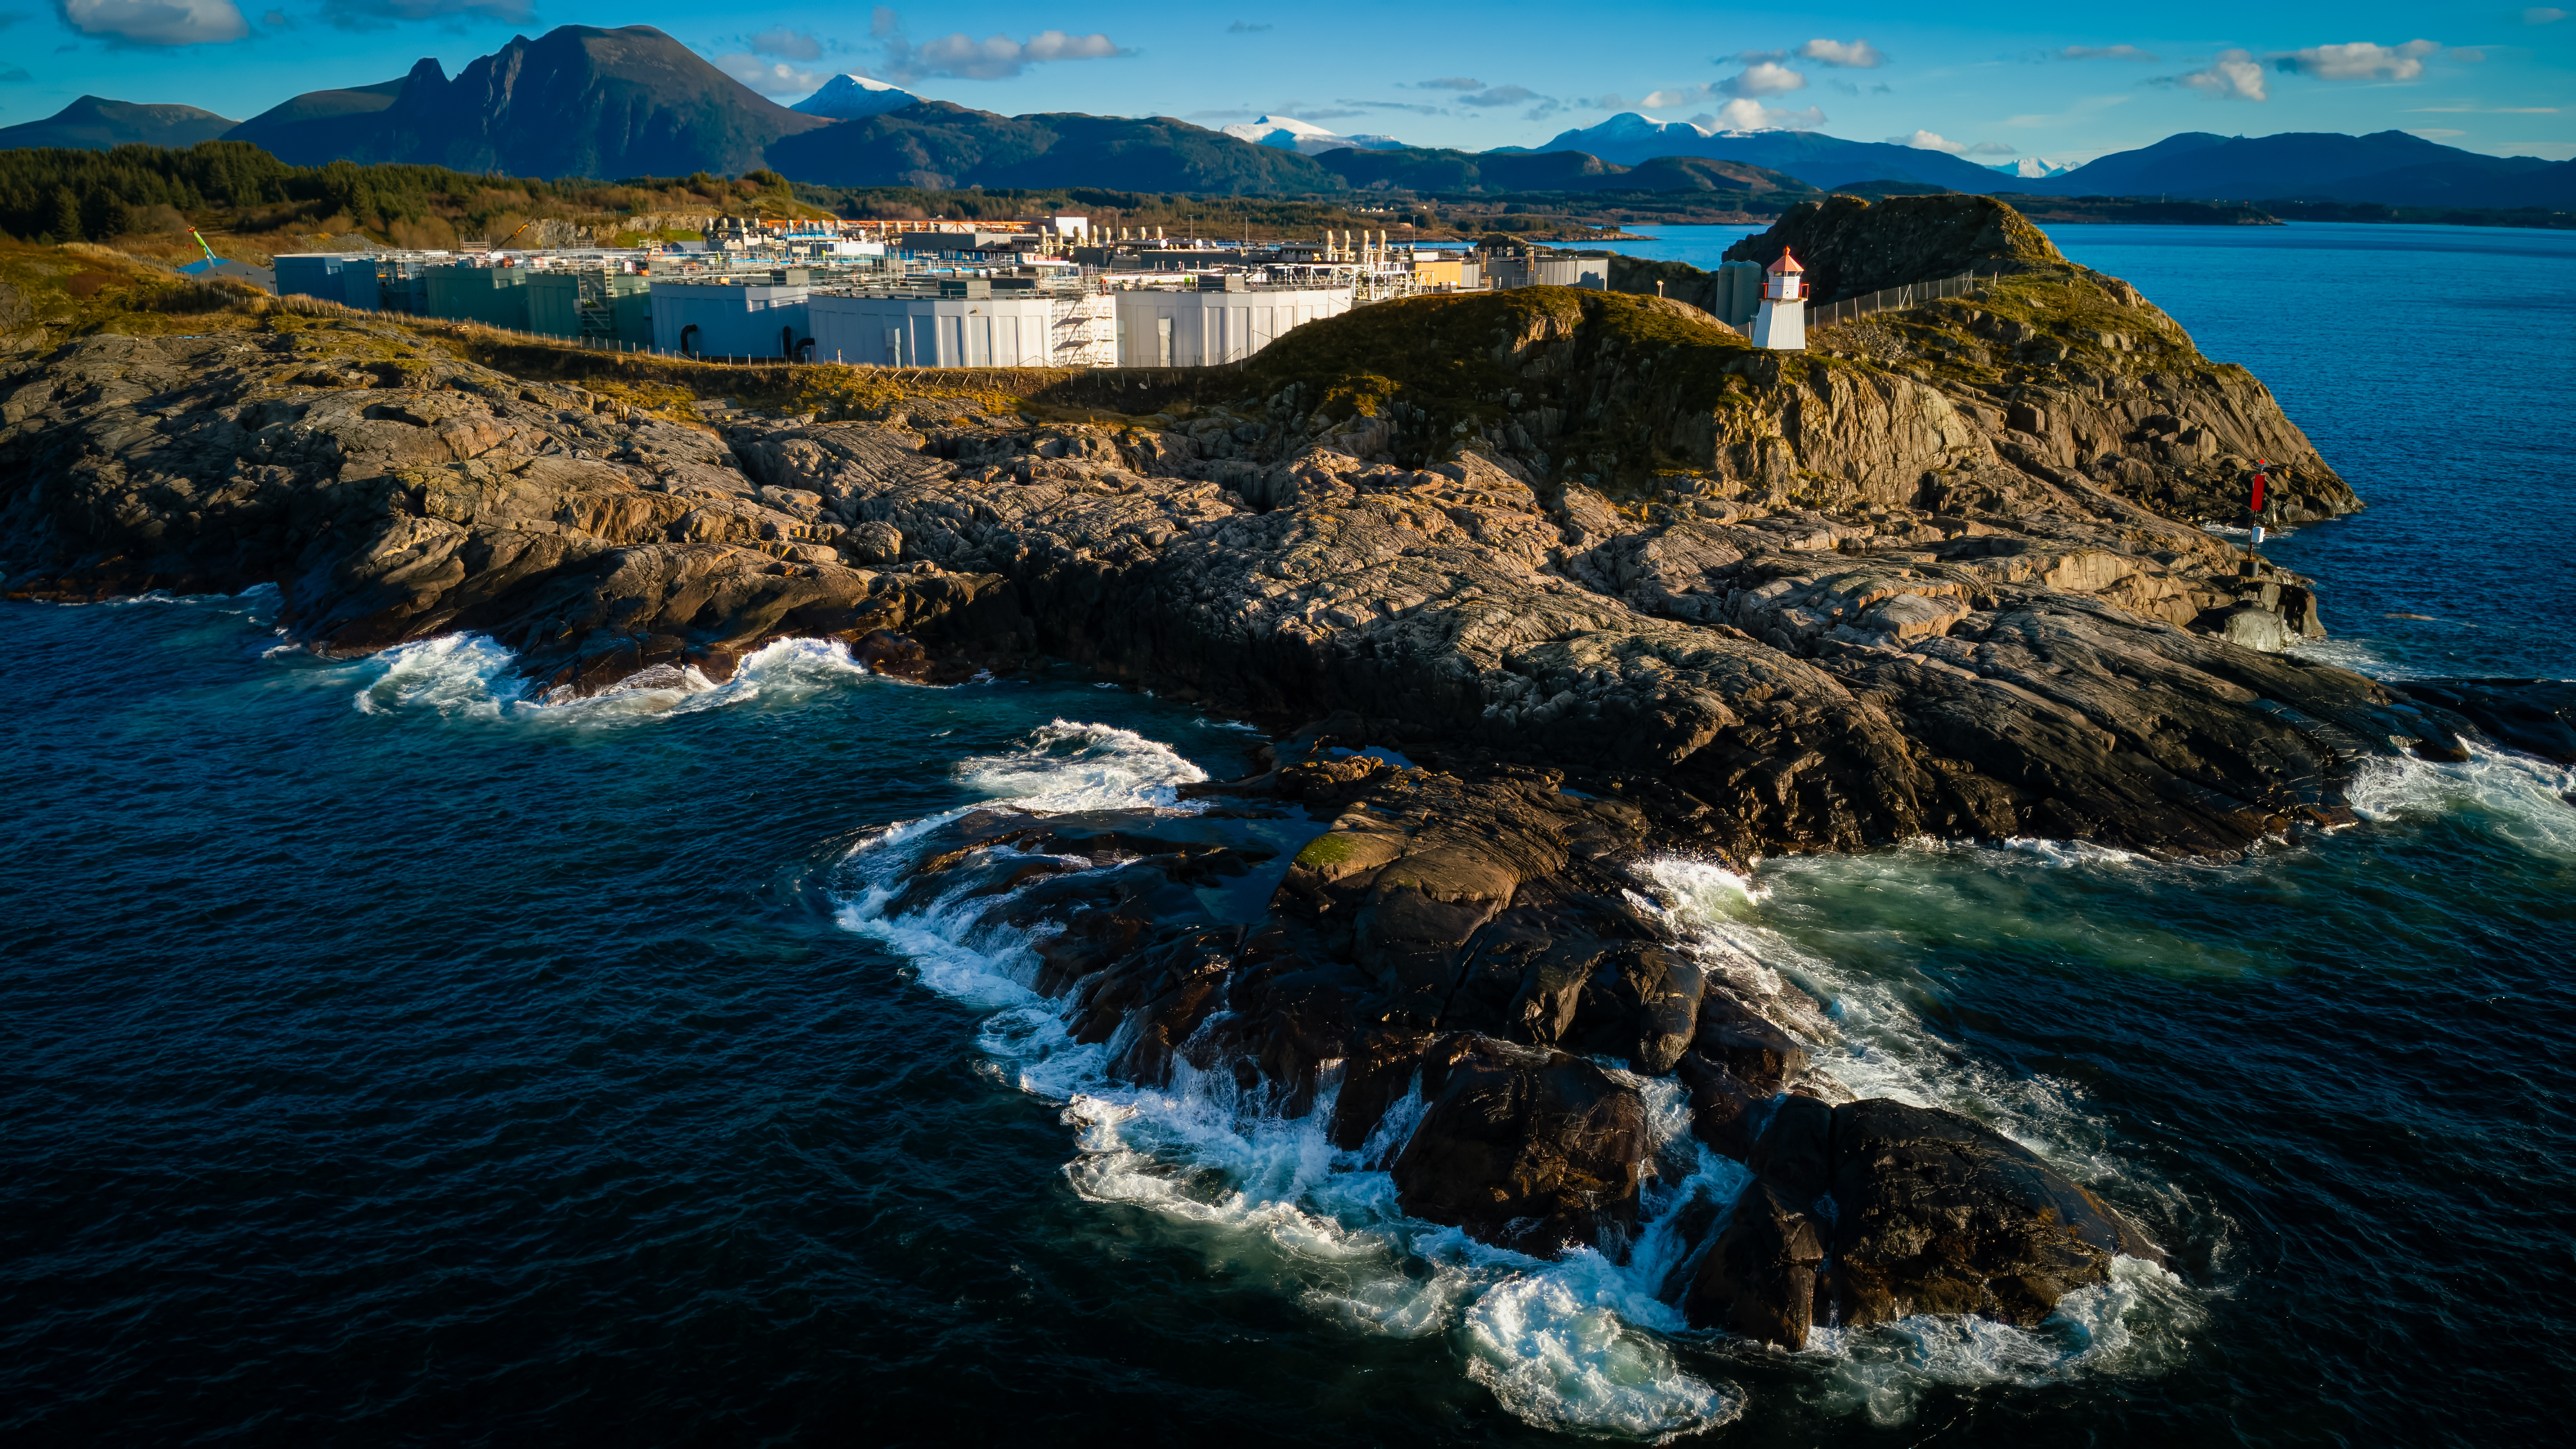
- Indre Harøy phase 2 progressing according to plan, first smolt release scheduled in week 17. Plan to release 2.8 million smolt in 2026, up 65 % from 2025.
- High supply growth continued to pressure market prices through the quarter, impacting financial results.
- Breakeven farming operations net of phase 2 ramp-up costs. Revenues of 98.7 NOKm, farming EBITDA -1.3 NOKm and group EBITDA -8.4 NOKm.
- Updated partnership model in Korea reflecting Salmon Evolution's strategic priorities in the near to medium term, hereunder continued focus on operational excellence and phase 2 project execution.
Key figures
| Operational | Q4 2025 | Q4 2024 | 2025 | 2024 |
|---|---|---|---|---|
| Standing biomass (tonnes, LW) | 3 115 | 2 023 | 3 115 | 2 023 |
| Net growth (tonnes, LW) | 1 592 | 1 518 | 6 451 | 5 706 |
| Harvest volumes (tonnes, HOG) | 1 203 | 1 729 | 4 403 | 4 891 |
| All-in price realization/kg (NOK)1 | 73,8 | 82,4 | 69,5 | 93,4 |
| Farming EBITDA/kg | -1,1 | 8,9 | -9,0 | 23,0 |
| Farming costs/kg (NOK) | 72,6 | 70,9 | 77,1 | 67,8 |
| Financial (in NOK thousand) | Q4 2025 | Q4 2024 | 2025 | 2024 |
| Operating revenues | 98 739 | 149 535 | 326 022 | 471 573 |
| Operational EBITDA2 | -8 431 | 9 248 | -78 686 | 71 415 |
| Operational EBIT2 | -25 177 | -11 291 | -158 906 | -4 727 |
| Profit (loss) before tax | 1 147 | -26 925 | -171 601 | -47 405 |
| Cash flow from operations | 18 746 | 965 | -59 052 | 43 331 |
| Operational EBITDA Farming Norway2 | -1 304 | 15 325 | -39 483 | 112 425 |
| Capital structure (in NOK thousand) | Q4 2025 | Q4 2024 | 2025 | 2024 |
| Cash flow from investment activities | -386 911 | -155 496 | -1 252 431 | -342 562 |
| Cash flow from financing activities | 375 247 | 20 742 | 1 045 458 | 342 297 |
| Cash and cash equivalents | 163 438 | 429 462 | 163 438 | 429 462 |
| Net Interest-bearing debt | 1 757 437 | 313 111 | 1 757 437 | 313 111 |
| Equity ratio (%) | 49 % | 70 % | 49 % | 70 % |
| Profitability | Q4 2025 | Q4 2024 | 2025 | 2024 |
| Earnings per share (NOK) | 0,00 | 0,00 | -0,37 | -0,11 |
| 1 Calculated on a back to farm basis and adjusted for transport cost to Norway border (Sisalmoni equivalent) | ||||
| 2 Before fair value adjustment related to biological assets | ||||